Is Hazard Insurance the Same as Homeowners Insurance?
Key Takeaways
Hazard Insurance Is Part of Your Homeowners Policy
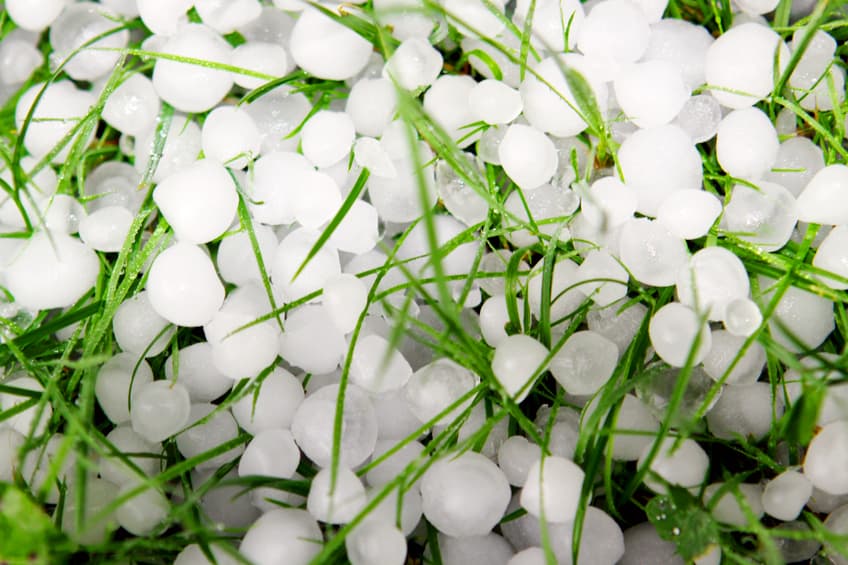
"Hazard insurance" is not a separate product — it’s the portion of your homeowners policy that covers structural damage from perils like fire, windstorms, hail, theft, and vandalism. If you have a standard homeowners policy, you already have it.
Lenders Use the Term — Not Insurers
Mortgage lenders ask for "proof of hazard insurance" because the home’s structure is their collateral. They’re simply asking for the dwelling coverage section of your existing homeowners policy.
Floods and Earthquakes Still Require Separate Policies
Standard homeowners insurance does not cover flood or earthquake damage. Homeowners in high-risk areas need to purchase these separately to have full protection.
When you’re buying a home or reviewing your insurance policy, you might come across the term “hazard insurance” and wonder how it fits in with your homeowners insurance. Are they the same thing? Do you need both?
The truth is, these terms are often used interchangeably, but they’re not exactly identical. In this guide, we’ll break down what hazard insurance really means, how it relates to homeowners insurance, and what coverage you need to protect your property.
What Is Hazard Insurance?
Hazard insurance is the part of your homeowners insurance policy that helps pay for damage to your home caused by specific perils, like fire, windstorms, hail, or vandalism. It’s designed to cover the structure of your home if it’s damaged or destroyed by one of these covered events.
You’ll often hear the term “hazard insurance” used by mortgage lenders. That’s because lenders usually require this coverage to protect their financial investment in your home. However, it’s usually part of your overall homeowners insurance, not a separate policy.
What Does Homeowners Insurance Cover?
Homeowners insurance offers broader protection than hazard insurance alone. While it does include hazard coverage for damage to the structure of your home, it also covers other structures on your property, personal property, liability, and additional living expenses if you’re temporarily displaced.
A standard homeowners policy helps protect your home’s structure from covered events, your belongings from loss or damage, and your finances if someone is injured on your property and you’re held responsible.
Hazards Covered Under a Standard Policy
Most standard homeowners insurance policies that include hazard insurance cover perils like:
- Fire and smoke
- Hail and windstorms
- Theft and burglary
- Vandalism
- Lightning strikes
Keep in mind that some hazards—like floods or earthquakes—typically aren’t covered under a standard policy. You’ll need to purchase separate coverage for those types of risks.
Hazard Insurance vs. Homeowners Insurance
Hazard insurance and homeowners insurance aren’t two separate policies. Hazard insurance is just the name of the part of your homeowners insurance that covers physical damage to your home from certain risks.
Why Lenders Refer to Hazard Insurance
The term “hazard insurance” is most commonly used by mortgage lenders. When they require proof of it, they’re really asking for the portion of your homeowners policy that protects the structure of the home. This is because the home itself is the collateral for the loan, and lenders want to make sure it’s protected from damage that could reduce its value.
Terminology can vary from one financial institution to another, which is part of why the term “hazard insurance” often causes confusion. But at the end of the day, if you have a standard homeowners insurance policy, you already have the hazard coverage your lender is asking for.
Do You Need Both Hazard and Homeowners Insurance?
You don’t need to buy separate hazard insurance if you already have a homeowners insurance policy—it’s built in. The dwelling coverage section of your policy is what mortgage lenders are referring to when they ask for hazard insurance.
Still, it’s a good idea to review your declarations page to see exactly what’s covered and how it’s broken down. This page outlines your coverage limits, deductibles, and the specific protections included in your policy.
If you’re unsure about what your policy includes or whether it meets your lender’s requirements, talk to a GEICO Insurance Agent. They can help you understand your coverage and make sure everything is in place to protect both your home and your peace of mind.
Additional Coverage Options to Consider
While a standard homeowners insurance policy offers strong protection, there are times when additional coverage can help fill in the gaps. Depending on where you live and what you own, these options might be worth exploring:
- Flood Insurance: Not included in standard policies. If you live in a flood-prone area, a separate flood insurance policy through the National Flood Insurance Program (NFIP) or a private insurer may be essential.
- Earthquake Insurance: Also not part of most standard policies. Homeowners in areas with frequent seismic activity should consider adding this coverage.
- Umbrella Insurance: This provides an extra layer of liability protection beyond your standard homeowners policy. It can be especially useful if you have high-value assets or want added peace of mind.
It’s important to reassess your coverage after making home improvements or purchasing high-value items. This helps keep your policy as accurate and effective as possible.
Protect Your Home Through GEICO Insurance Agency: Hazard and Homeowners Insurance
Understanding the difference between hazard insurance and homeowners insurance can help you make more informed decisions about your policy. While hazard insurance covers specific risks, it’s just one part of a complete homeowners insurance package.
Ready to get personalized coverage for your home? Get a free homeowners insurance quote through GEICO Insurance Agency today and see how easy it is to protect what matters most.